Coastal insurance is an important line item in a Sussex County home purchase or sale—not an afterthought to address just before settlement. Premiums can vary substantially based on a property’s location, elevation, age, roof condition, coverage choices, and insurer availability. Knowing what to request early can help buyers compare homes more clearly and help sellers avoid surprises during negotiations.
Why Coastal Insurance Deserves an Early Look
Along Delaware’s coast, a home’s insurance profile is shaped by more than its price tag. Buyers may need homeowners insurance plus separate flood coverage, while wind and hail deductibles can affect the out-of-pocket cost after a covered event. A property near the bay, ocean, marsh, canal, or other low-lying area may have different underwriting considerations than a home farther inland, even when the homes look similar on a listing sheet.
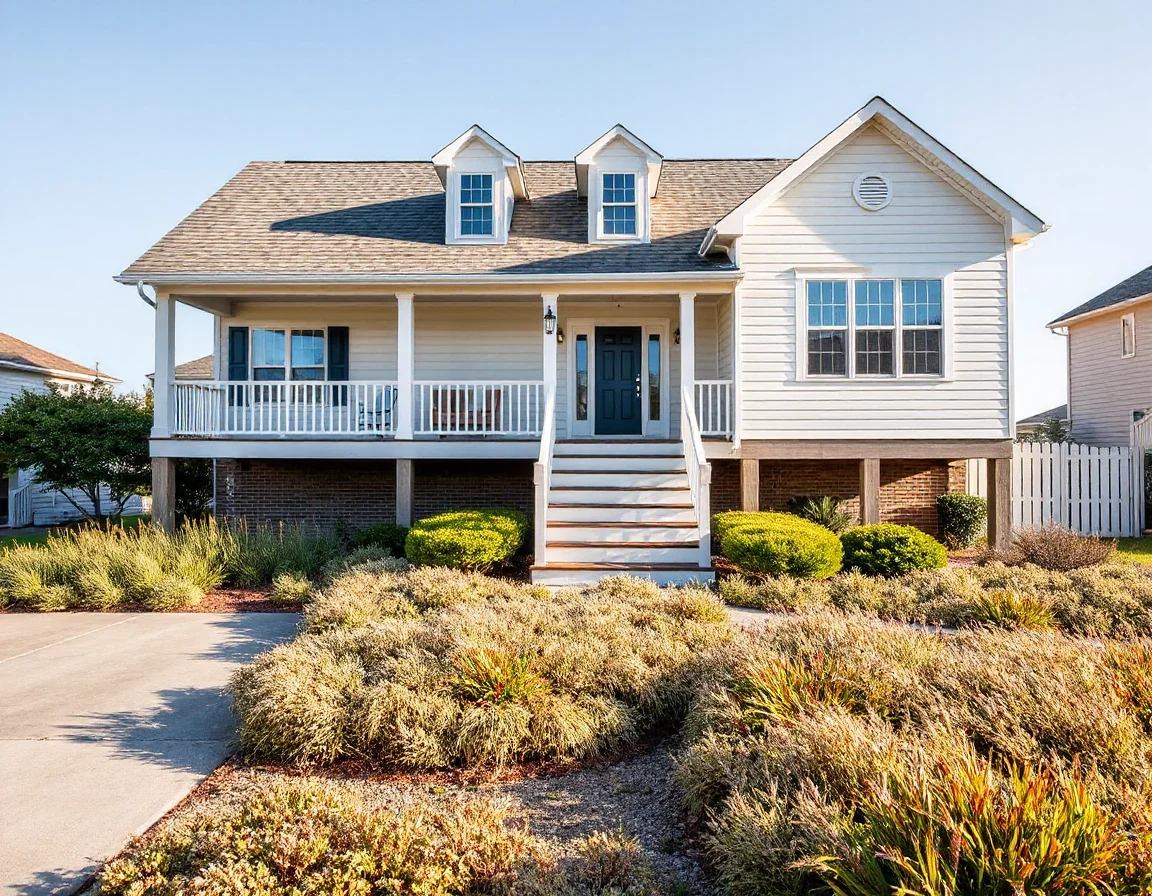
For buyers, the key is to make insurance research part of due diligence as soon as a promising property is identified. A quick conversation with an insurance professional can provide an initial estimate, identify likely policy requirements, and flag documents that may be useful before writing an offer. Waiting until the final days of a contract can create unnecessary pressure, particularly if an insurer needs more information about the roof, electrical system, prior losses, flood zone, or replacement-cost calculations.
For sellers, insurance costs can influence the questions prospective buyers ask and the comparisons they make among nearby listings. Keeping property records organized—such as roof invoices, mitigation improvements, elevation certificates if available, and maintenance documentation—can make it easier to respond accurately. These records do not guarantee a particular premium or coverage decision, but they can give buyers and their insurers a clearer starting point.
The most useful insurance estimate is property-specific. Two homes on the same street can produce different quotes because construction details, deductibles, claims history, and coverage limits all matter.
It is also helpful to separate the concepts of insurance cost and property value. A higher premium does not automatically mean a home is less desirable, and a lower quote is not the only measure of coverage quality. Buyers should review deductibles, exclusions, limits for personal property and additional living expenses, and the difference between actual cash value and replacement-cost coverage. A policy that appears less expensive upfront may carry a larger deductible or narrower protection after a loss.
The Main Factors Behind a Premium
Location is often the first factor people consider, and it matters. Flood maps, proximity to water, drainage patterns, and local elevation can all affect flood-insurance availability and pricing. Lenders may require flood insurance when a financed property is located in a designated Special Flood Hazard Area, but buyers can still choose to explore flood coverage for homes outside those zones. Flood risk is not limited to one map designation, and policy options should be discussed with a qualified insurance provider.
Construction and upkeep matter just as much. Insurers commonly look at the age and condition of the roof, roof shape and attachments, siding, windows, doors, heating systems, plumbing, electrical panels, and foundation. In a coastal setting, materials designed to handle wind, salt air, moisture, and changing weather can be relevant to underwriting. Recent updates may help support an application, but the insurer determines which improvements affect eligibility or price.
Deductibles deserve special attention because they can be percentage-based rather than a single fixed dollar amount. On a higher-priced coastal property, a percentage wind deductible can represent a meaningful expense if a covered loss occurs. Buyers should ask insurers to explain when the deductible applies, how it is calculated, and whether alternate deductible options are available. This helps turn an unfamiliar policy detail into a practical budget decision.
Coverage limits are another part of the equation. The amount needed to rebuild a home may not match its purchase price, land value, or recent appraisal. Building materials, labor costs, specialty finishes, detached structures, and local rebuilding demand may all affect replacement-cost estimates. This is especially important for beach homes, investment properties, and properties with upgraded finishes, where a standard estimate may not capture every feature without a detailed conversation.
Insurance markets also change. Carrier guidelines, reinsurance costs, weather losses, and regional capacity can affect what is available from one year to the next. That is why it can be worthwhile to seek more than one quote, while comparing like-for-like coverage rather than focusing only on the annual premium. An independent insurance professional can explain differences among proposals and help buyers understand the choices available at that time.
Ask for the annual premium, every deductible, flood-policy details, and the estimated replacement-cost figure in writing before comparing quotes side by side.
A Practical Plan for Buyers
A thoughtful approach begins before the offer. If coastal insurance is a major consideration, ask early whether the seller has an elevation certificate, flood-policy information, roof age documentation, and records of major updates. These items may not answer every underwriting question, but they can shorten the time needed for an insurer to prepare a more tailored estimate. Your real estate contract and lender can also help define timing for any insurance-related contingencies or requirements.
After identifying a home, share the complete address and as many property details as possible with an insurance professional. Confirm whether flood coverage is required by the lender, whether it is separately billed, and whether a policy can be bound in time for settlement. Ask how wind, named storm, water backup, ordinance or law, and loss-of-use coverage are handled. The right questions make it easier to compare options without assuming that one policy format fits every property.
Buyers should also keep a reserve for routine ownership costs beyond the policy premium. Coastal ownership often includes maintenance items such as roof inspections, exterior sealing, drainage attention, HVAC servicing, and monitoring for moisture. Preventive care can protect a home’s condition and may make future insurance renewals easier to navigate, although each carrier applies its own standards.
Estimate your monthly homeownership costs
How Sellers Can Prepare Without Overpromising
Sellers do not need to predict a buyer’s insurance quote, because premiums and eligibility depend on the buyer’s selected coverage and the insurer’s current guidelines. What sellers can do is present accurate property information. A concise file with permits, receipts, roof certifications, improvement dates, utility details, and any available flood-related documents can reduce uncertainty and support a smoother due-diligence period.
If a property has features such as impact-rated openings, storm shutters, a raised mechanical system, updated roof attachments, or improved drainage, describe them factually and retain supporting records where possible. Avoid making promises about premium reductions. Instead, allow buyers and their insurance advisors to determine how those features may be evaluated. Clear documentation is more useful than broad claims.
Pricing and negotiation should also account for the reality that buyers may be evaluating total carrying costs, not just the list price. When a question about insurance arises, a prompt, organized response can keep the transaction moving. A local real estate professional can help coordinate property details with the appropriate parties while leaving coverage advice and policy decisions to licensed insurance specialists.
Talk through your Sussex County real estate plans
Make Insurance Part of the Bigger Coastal Picture
Sussex County offers a broad range of homes, from beach-area condominiums and townhomes to inland properties near Rehoboth Beach, Lewes, Bethany Beach, Fenwick Island, Milton, and surrounding communities. Each location and property type brings its own mix of maintenance, association, financing, and insurance considerations. The strongest decisions come from reviewing the full picture early rather than treating insurance as a final checklist item.
For both buyers and sellers, preparation creates options. Gather reliable property information, obtain timely quotes from qualified professionals, review the policy terms carefully, and allow enough room in the transaction timeline for follow-up questions. With those steps in place, coastal insurance becomes a manageable part of owning or transferring a Sussex County home—and one more detail that can be addressed with confidence.