A Sussex County vacation home can offer beach access, potential rental income, and a future resale opportunity—but the nightly rate is only the beginning of the calculation. Compare seasonal demand with insurance, management, maintenance, financing, and the time you plan to use the property yourself. A realistic budget can help you decide whether the numbers support the experience you want.
Start with the purpose of the purchase
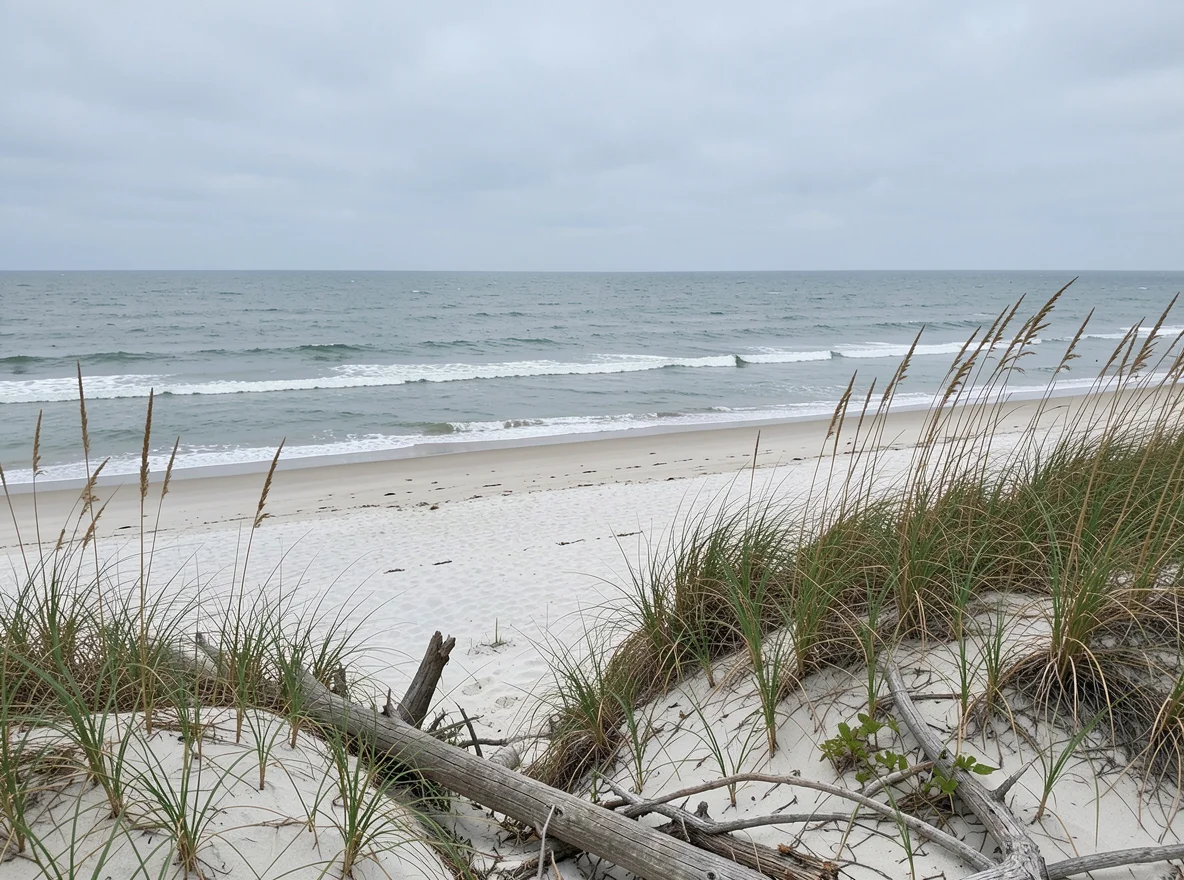
A morning walk near the dunes and a porch for unwinding after dinner are easy to picture. The financial side takes a little more work. Before comparing homes in Bethany Beach, Lewes, Rehoboth Beach, or inland communities such as Ocean View and Selbyville, decide how much weight to give personal enjoyment, rental cash flow, and long-term resale.
Those goals can pull in different directions. Reserving the home for your own use during popular summer weeks may reduce the income available to offset expenses. A property with attractive rental potential may also require more frequent cleaning, repairs, and coordination than a home used only occasionally.
Location affects more than the purchase price. Distance to the beach, parking, access to dining and recreation, community amenities, and the property’s layout can all influence a guest’s decision. Ask a local real estate professional to help compare properties against your specific plans rather than assuming every beach-area home will perform alike.
Calculate the full cost of ownership
The down payment and mortgage are important, but they are not the whole budget. Request property-specific figures before making an offer, especially for insurance and association fees, which can vary substantially from one address to another.
- Purchase and setup: Include closing costs, inspections, furnishings, linens, kitchen supplies, and any work needed before guests arrive.
- Recurring expenses: Estimate property taxes, homeowners insurance, utilities, internet, association dues, landscaping, and routine maintenance.
- Rental operations: Account for management or booking fees, cleaning arrangements, supplies, permits, and any applicable lodging taxes.
- Reserves: Set money aside for larger replacements, unexpected repairs, and periods when the property is vacant.
Coastal exposure deserves particular attention. Ask an insurance professional for quotes based on the actual property and discuss wind coverage, deductibles, and whether separate flood insurance is appropriate or required. Standard homeowners coverage generally does not cover flooding, and a flood-zone designation alone does not tell you every risk or cost.
Get insurance quotes before your inspection and financing deadlines expire. A change in premium, deductible, or coverage requirement can materially alter the property’s projected return.
If the home is in a condominium or homeowners association, review its budget, reserves, insurance responsibilities, rental restrictions, and any pending or proposed special assessments. Verify what the association covers rather than assuming an amenity fee includes exterior maintenance or insurance for your unit.
Build an income estimate from the calendar up
Start with comparable rentals that resemble the property in location, size, amenities, and condition. Look beyond advertised peak-week rates: a strong estimate also considers shoulder-season pricing, vacancies, booking fees, and the weeks you intend to keep for yourself.
A useful starting formula is booked nights multiplied by average nightly rent. Then subtract the operating expenses associated with earning that income. Avoid treating every available night as booked, and ask a rental manager how much of the projected calendar depends on summer demand.
Cleaning fees need careful handling. If guests pay a separate cleaning charge that is passed directly to a cleaner, keep that charge and expense consistent in your forecast rather than counting the fee as profit. Also distinguish rental income from lodging taxes collected from guests and remitted to the appropriate authority.
Rules can differ by municipality, unincorporated county location, and association. Before relying on short-term rental income, confirm whether the property can be rented as planned, what registrations or inspections apply, and which taxes must be collected. A listing’s past rental activity is not a substitute for checking current requirements.
An illustrative return calculation
Suppose a hypothetical property costs $600,000 and rents for 120 nights at an average of $350 per night. That produces $42,000 in annual gross rental income. These are example assumptions, not a forecast for any Sussex County property.
- Property tax: $4,500
- Insurance: $4,000
- Association dues: $3,000
- Utilities and internet: $3,600
- Maintenance: $5,000
- Management at 18% of gross rent: $7,560
- Booking fees at 3% of gross rent: $1,260
- Supplies and other operating costs: $2,080
These assumed expenses total $31,000, leaving $11,000 in annual operating income before mortgage payments, income taxes, depreciation, and major capital replacements. Dividing that amount by the $600,000 purchase price gives an unleveraged operating yield of about 1.8%. Actual costs and income could differ considerably.
Now add financing. A hypothetical $480,000 loan at a fixed 7% rate over 30 years has a principal-and-interest payment of approximately $3,193 per month, or $38,318 per year. Subtracting that from the $11,000 operating income produces approximately negative $27,318 in annual cash flow, before income taxes and major capital expenses. The example excludes any tax benefit or appreciation and assumes the loan is available on those terms.
Gross rental income is not cash flow. In this example, $42,000 in bookings becomes $11,000 before financing—and a financed purchase has a substantial annual shortfall.
The initial cash requirement matters, too. With a 20% down payment, $18,000 in assumed closing costs, and $15,000 for setup, the buyer would need about $153,000 upfront, plus any desired reserves. Use actual lender estimates and vendor quotes to replace these illustrative figures.
Test the downside before counting on the upside
Build at least three versions of your budget: a base case, a stronger booking year, and a cautious year with fewer rented nights or higher expenses. Consider what happens if insurance rises, an appliance fails during peak season, or you reserve two prime weeks for personal use. If the cautious case would strain your finances, revisit the price, down payment, or ownership plan.
Different management arrangements also change the equation. Full-service management may cover guest communication and coordination, while self-management can reduce some fees but requires time and dependable local support. Ask exactly which services are included, how maintenance is approved, and whether extra charges apply.
Consider resale from the first showing
Future appreciation is never guaranteed. When evaluating a purchase, look at recent comparable sales, property condition, ongoing costs, and features that tend to matter to a broad range of buyers: functional layout, parking, outdoor space, and convenient access to local amenities. A well-maintained property with clear documentation can be easier to evaluate when it is time to sell.
Rental history can be useful, but keep records of actual income and expenses rather than relying on projected figures. Track improvements separately from routine repairs, retain invoices, and discuss potential income-tax consequences—including depreciation and possible recapture—with a qualified tax professional. State and federal rules depend on how the property is used.
Whether your priority is time at the shore, rental income, or a combination of both, the best decision starts with property-specific numbers and a plan for the costs you cannot predict precisely. Compare homes with the calendar, cash reserves, and eventual sale in mind, and let the financial picture be as clear as the appeal of the coast.