An Ocean View rental can look promising on a listing sheet and still underperform once property taxes, insurance, seasonal expenses, and vacancy are counted. A practical cash-flow plan turns those recurring costs into clear operating targets, helping owners make decisions based on net income rather than headline rent alone. The goal is not simply to collect more rent; it is to protect the return the property is designed to produce.
Start With the Income That Actually Reaches the Bottom Line
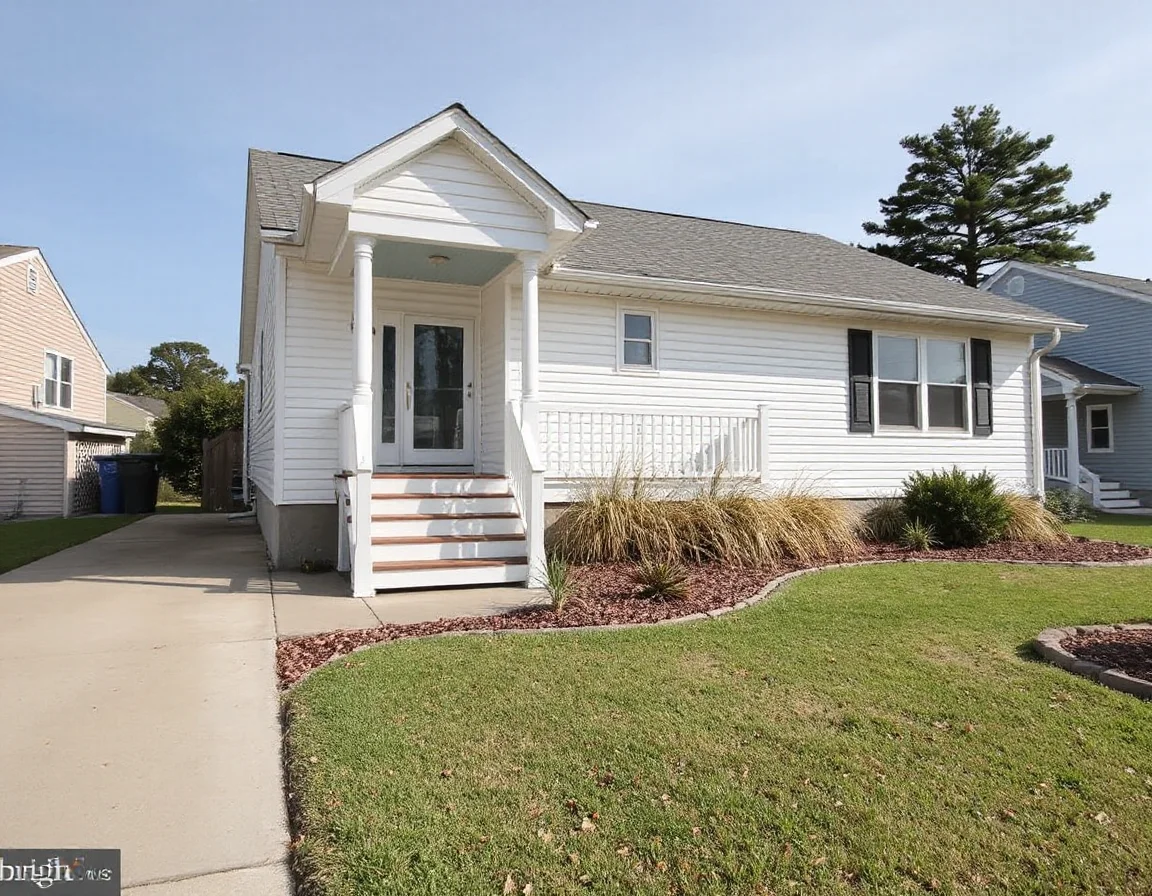
Ocean View, Delaware sits within reach of the South Delaware Beaches, making rental-property ownership a conversation about both location and operations. Owners may see demand shift across the calendar, with stronger activity around beach-season travel and a different pace during quieter months. That makes it especially important to separate gross scheduled rent from the income that remains after routine costs, turnover, repairs, management, taxes, insurance, and vacancy have all taken their share.
A useful starting point is an annual operating statement. List expected rent by month, including any permitted fees, then subtract the predictable annual expenses. The result before mortgage payments is commonly called net operating income, or NOI. From there, subtract principal and interest payments to see the property’s pre-tax cash flow. This simple sequence prevents a common mistake: treating a high monthly rent estimate as proof that a property will generate a strong return.
For a seasonal or beach-area rental, use conservative assumptions. Include a vacancy allowance even if the property has performed well in the past, and do not assume every peak-season date will be booked at the highest rate. If the home is rented long-term, account for potential gaps between leases, marketing costs, and the occasional make-ready period. If it is rented on a shorter-term basis where allowed, factor in cleaning, supplies, booking-platform charges, local compliance obligations, and more frequent wear on furnishings.
A rental’s strongest month should not set the budget. Build the annual plan around an achievable occupancy and rate scenario, then treat above-plan revenue as upside rather than a requirement.
Owners can also compare performance using cash-on-cash return: annual pre-tax cash flow divided by the cash invested to acquire and prepare the property. This metric will not answer every question, but it puts the focus on funds actually committed to the investment. It is particularly helpful when comparing properties with different purchase prices, financing structures, or furnishing needs.
Put Taxes on the Calendar, Not on the Back Burner
Property taxes are a recurring ownership cost, not an afterthought. In Delaware, the tax bill can reflect county, school-district, and other local components, and the amount may differ from one property to another. A buyer should review the actual current bill, ask whether there are exemptions or assessment details relevant to the parcel, and understand when payments are due. Do not rely solely on a previous owner’s annual total when planning future expenses.
For investment-property accounting, keep tax documents organized from the first day of ownership. Closing statements, annual tax bills, improvement invoices, repair receipts, utility records, and management reports all support clearer bookkeeping. Tax treatment can vary based on how the property is used, rented, financed, and maintained, so owners should work with a qualified tax professional for advice tailored to their situation.
Capital improvements deserve separate attention from ordinary repairs. Replacing a damaged fixture, servicing HVAC equipment, and repairing a small leak are different from a larger upgrade such as a roof replacement, major systems work, or a substantial renovation. Keeping these categories distinct makes the operating picture more accurate and gives a tax professional better records to evaluate. It also helps owners avoid understating the true cost of preserving the property over time.
When reviewing projected ROI, include a reserve for long-term replacement needs. Appliances, exterior finishes, flooring, mechanical equipment, decking, and furnishings do not last forever. A property may show positive cash flow while still falling behind if there is no reserve for the next major expense. Setting aside a fixed monthly amount creates a more durable plan than reacting only when something breaks.
Review tax bills and improvement records at least once a year before renewal and budgeting decisions. Clean records make it easier to measure performance and prepare for large expenses without surprise.
Insurance Is a Core Operating Expense
Insurance deserves the same attention as rent projections because coastal and near-coastal markets can involve coverage decisions beyond a standard homeowners policy. Depending on the property’s location, construction, use, lender requirements, and flood-zone information, an owner may need to evaluate landlord coverage, wind or hail provisions, flood insurance, liability limits, loss-of-rent protection, and deductibles. The right approach is to request quotes based on the actual intended rental use rather than assuming a personal-use policy will provide the needed protection.
Premiums can change at renewal, and deductibles can have a meaningful effect on an owner’s emergency cash needs. Compare the policy details, exclusions, coverage limits, and replacement-cost assumptions—not just the annual premium. A lower premium may come with a deductible or limitation that changes the real risk retained by the owner. Ask an insurance professional to explain the policy in plain language and revisit coverage after major improvements or changes in rental strategy.
Property condition can influence both operating reliability and insurability. Routine roof inspections, well-maintained gutters, secure exterior elements, functional drainage, updated mechanical systems, and documented maintenance can reduce preventable surprises. These efforts also help protect the guest or tenant experience, preserve the home’s presentation, and support consistent rental readiness.
Use Cash Flow to Guide Pricing and Improvements
Once taxes, insurance, reserves, utilities, management, financing, and vacancy are included, owners can make more confident choices about pricing. If comparable rentals support a higher rate, test the change within a realistic occupancy plan. If the market does not support the desired increase, look for expenses that can be managed without reducing property quality. Small improvements to presentation, maintenance planning, and operational efficiency can be more productive than simply trying to push rates beyond what the market supports.
Before undertaking a renovation, define the reason for it. Will it reduce future maintenance, improve durability, support a stronger rental position, or make the property easier to market? A polished kitchen, refreshed bath, durable flooring, exterior updates, or professional staging may create value, but each project should be measured against its full cost, anticipated maintenance, and likely contribution to income or resale appeal. Not every upgrade needs to be luxury-level to be useful.
It also helps to review the property quarterly. Compare actual income and expenses with the budget, note changes in occupancy or utility use, and identify repairs that may become larger if deferred. Over time, this history becomes one of the owner’s best decision-making tools. It reveals whether an expense spike was a one-time event, a seasonal pattern, or a sign that the operating plan needs revision.
Strong ROI in Ocean View is built through disciplined assumptions, complete records, appropriate coverage, and regular review. When the numbers are honest, owners can decide whether to hold, improve, refinance, adjust pricing, or prepare for a sale with far more clarity. A beach-area investment is not just a property; it is an operating business with an income statement that deserves consistent attention.