Berlin, Maryland investment property decisions come down to more than a purchase price or a promising nightly-rate estimate. A useful comparison puts projected income beside financing, operating reserves, seasonality, maintenance, and the time required to manage the property well. This guide offers a practical framework for evaluating cash flow and ROI before making an offer.
Start With the Income Story, Not the Listing Price
Berlin offers access to a distinctive small-town setting in Worcester County, Maryland, with proximity to Ocean City, Assateague Island, West Ocean City, and regional employment centers. That location can create several potential rental strategies, from long-term leasing to furnished stays where permitted. The right strategy depends on the property, local rules, financing terms, and the demand pattern you can document rather than assume.
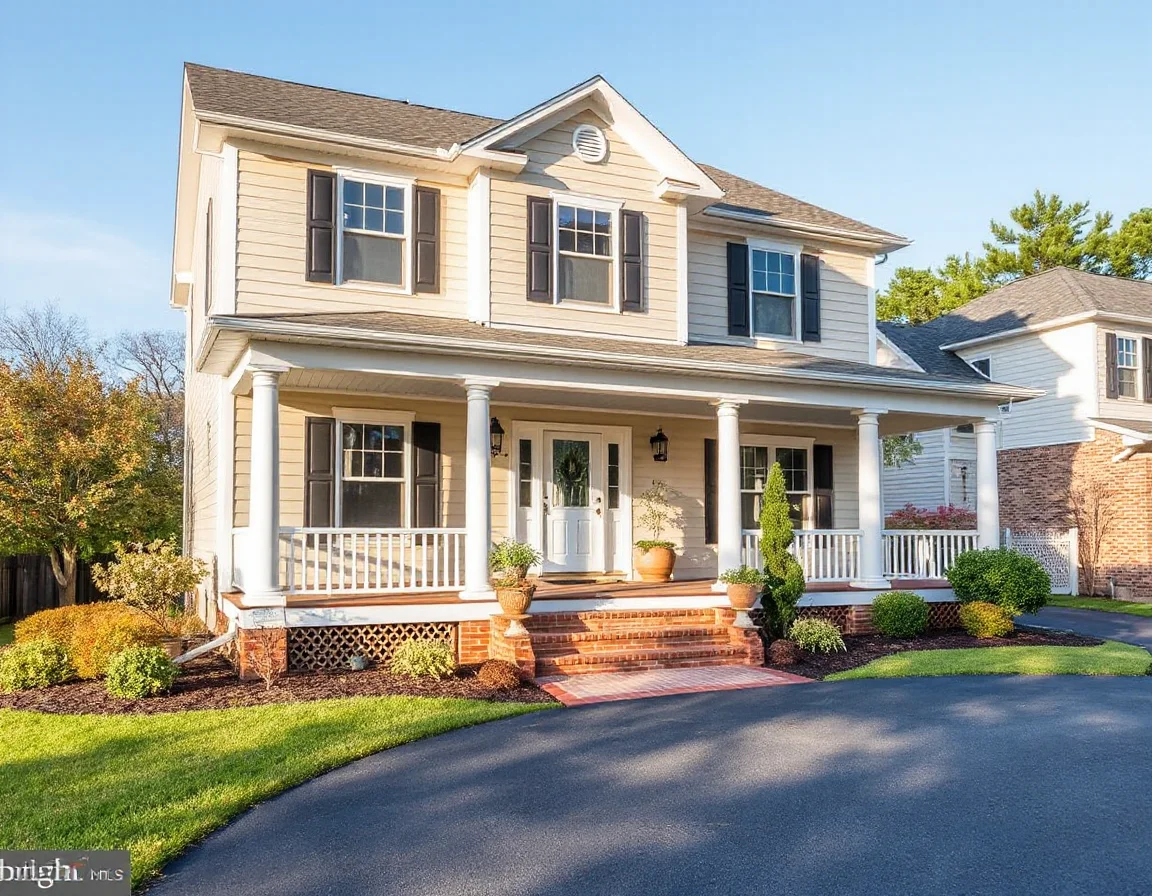
Begin with realistic gross income. For a long-term rental, review comparable leased properties with similar bedroom counts, condition, parking, outdoor space, and utility arrangements. For a furnished or short-term model, do not simply multiply a peak-season nightly rate by twelve months. Use conservative occupancy assumptions, account for lower-demand periods, and verify whether local registration, licensing, occupancy, tax, or association requirements apply to the specific address.
It also helps to compare more than one scenario. A property may produce steady income as a conventional lease, while a furnished seasonal approach could offer higher gross revenue but also higher turnover costs and more variable demand. Another property may be better suited to personal use plus limited rental availability. There is no universal “best” option; the strongest plan is the one supported by the property’s numbers and your desired level of involvement.
A peak-season estimate is only one line in the pro forma. Annual performance is shaped by shoulder-season demand, vacancy time, booking or leasing costs, and the reserve you keep for repairs.
When reviewing advertised rental figures, ask what is included. A monthly rent that appears strong can change quickly if the owner pays utilities, lawn care, furnishings, internet, trash service, or a portion of association fees. Likewise, a furnished rental’s gross revenue should be reduced by cleaning, linens, consumables, platform fees, management, and periodic replacement of household items. Comparing properties on a net operating basis creates a much clearer picture.
Build a Complete Expense List
Cash flow is the money remaining after income and recurring costs are considered. Investors sometimes focus on principal and interest while underestimating the items that make ownership operationally demanding. A careful budget should include fixed costs, variable costs, and a reserve for expenses that do not arrive every month.
A useful annual expense worksheet commonly includes:
- Mortgage principal and interest, if financing is used
- Property taxes and homeowner’s insurance
- Flood insurance when required or appropriate for the property’s location
- Condominium, homeowners association, or community fees
- Property management, leasing, booking, or platform fees
- Utilities, internet, lawn care, pest service, and trash collection when owner-paid
- Repairs, capital improvements, furnishings, and appliance replacement reserves
- Cleaning, supplies, and turnover costs for furnished rental models
- Accounting, licensing, inspections, and applicable lodging or rental taxes
For coastal and near-coastal markets, insurance and maintenance deserve particular attention. Salt air, humidity, wind exposure, drainage, roofs, exterior paint, decks, HVAC systems, and plumbing can influence long-term ownership costs. A home inspection provides an important snapshot, but it should not replace a forward-looking maintenance budget. Consider the age and condition of major systems, then plan for their eventual replacement.
Property taxes, insurance quotes, association documents, and utility history should be verified during due diligence rather than estimated from a listing description. If the property is in a community with an association, review rental restrictions, approval procedures, fees, reserve funding, and any rules affecting parking, amenities, pets, or lease duration. Those details can materially affect both income potential and resale flexibility.
Estimate a monthly property payment
Compare Cash Flow, Cap Rate, and Return on Cash
Once projected income and expenses are organized, several simple measures can help compare Berlin investment opportunities. None is perfect on its own, but together they make conversations more concrete. The goal is not to force every property into the same formula; it is to identify the tradeoffs you are accepting.
Net operating income (NOI) is gross income minus operating expenses, before debt service. It helps compare properties regardless of whether one buyer uses cash and another uses financing. Capitalization rate, or cap rate, is NOI divided by the purchase price. It offers a snapshot of property-level income performance, although it does not include mortgage terms, closing costs, or future repairs.
Cash flow before tax takes the analysis a step further by subtracting annual debt service from NOI. This is often the number buyers watch most closely because it reflects money remaining after recurring operations and financing. A property can have a respectable cap rate but limited cash flow if borrowing costs are high or the down payment is relatively small.
Cash-on-cash return compares annual pre-tax cash flow with the cash invested, including down payment, closing expenses, initial repairs, furnishings, and setup costs. This can be especially useful when comparing a turnkey property with one that requires updates. A lower-priced home needing substantial work may require more cash at the beginning than expected, even if its future revenue potential is appealing.
Use the same assumptions for every property you compare. If one projection includes a 5% vacancy reserve and another assumes full occupancy, the results are not meaningful side by side. A conservative spreadsheet may feel less exciting, but it gives you room to absorb an unexpected repair, a slower leasing period, or a change in financing costs without relying on optimistic outcomes.
Test the Numbers Under Different Conditions
A reliable investment analysis includes a stress test. Try reducing projected revenue, increasing insurance, adding a repair expense, or allowing for several weeks without income. Then ask whether the property still supports your goals. If the deal only works under ideal assumptions, it may deserve a closer review before you proceed.
For example, compare a base case with a cautious case. The base case might use documented comparable rents, typical operating costs, and a standard maintenance reserve. The cautious case could reduce revenue by 10% to 15%, increase repairs, and include an additional vacancy period. This exercise is not a prediction; it is a way to understand your margin for change.
Before calculating ROI, set aside funds for initial improvements and future capital items. A reserve can protect the property plan when an HVAC system, roof component, appliance, or exterior feature needs attention sooner than expected.
Timing matters as well. Berlin and the surrounding coastal region can experience seasonal shifts in visitor activity, inventory, and buyer competition. A property purchased during one season may show very different booking, leasing, or maintenance patterns during another. Reviewing a full year of comparable data where available can be more informative than relying on a single active listing or a short period of high demand.
Due Diligence Can Protect the Return
Before writing an offer, create a property-specific checklist. Confirm zoning and rental rules with the appropriate local sources, read association documents, obtain insurance guidance, inspect major systems, and estimate immediate improvement costs. If rental income is part of the plan, collect credible comparable data and identify the management process you would use. A well-maintained property with a clear operating plan can be easier to evaluate than one supported primarily by broad market assumptions.
It is also wise to separate investment performance from possible appreciation. Market value can change over time, but appreciation is not guaranteed and should not be the only reason a property appears attractive. A durable strategy considers the present-day cost of ownership, potential income, condition, location, and your anticipated holding period.
Berlin can offer compelling opportunities for buyers who approach the market with detailed assumptions and enough flexibility to adapt. Focus on verified expenses, conservative revenue projections, and a reserve that reflects the property’s age and use. With those fundamentals in place, you can compare prospective investments with more confidence and choose a property whose cash-flow story makes sense beyond the headline price.