A Selbyville investment property can offer income potential and long-term resale value, but the purchase price is only the first number to evaluate. A useful ROI review accounts for carrying costs, rental strategy, local rules, financing, and the property’s likely appeal when it is time to sell. The goal is not simply to find a home that looks profitable on paper—it is to build a durable plan around realistic assumptions.
Start With the Investment Plan, Not the Listing Price
Selbyville, Delaware, sits within reach of the South Delaware Beaches while offering a mix of established neighborhoods, newer communities, townhomes, condos, and detached homes. That range gives investors choices, but it also means two properties with similar prices can perform very differently. Before estimating returns, decide what role the property will play: a long-term rental, a seasonal rental where permitted, a personal-use property with occasional rental income, or a home held primarily for future resale.
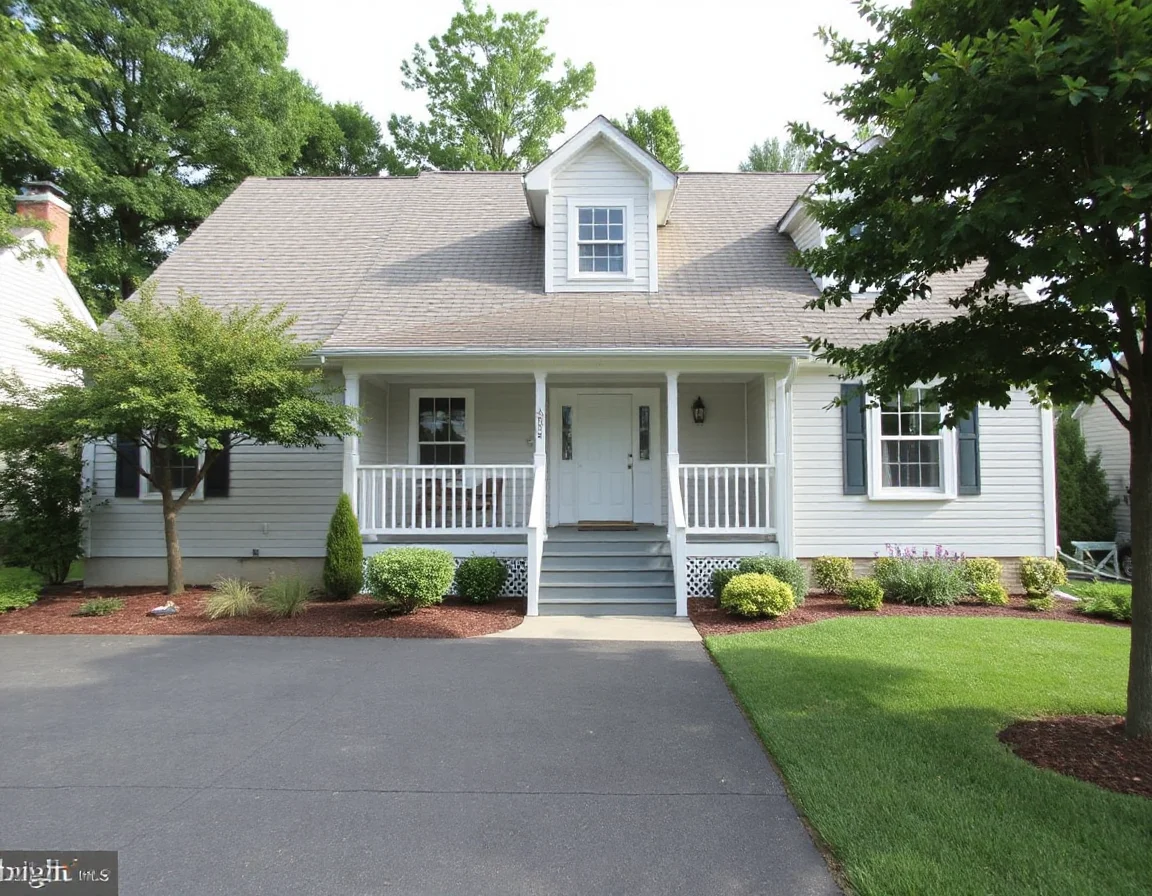
Every investment calculation should begin with a clear use case. A home intended for annual tenants may call for durable finishes, dependable appliances, straightforward landscaping, and predictable operating expenses. A property considered for shorter stays may require different furnishing, turnover, marketing, and management assumptions. Each approach can work, but the income model and workload are not interchangeable.
It is also important to confirm what is allowed before treating projected rent as guaranteed. Review local rental requirements, community association documents, lease restrictions, minimum rental periods, registration requirements, parking rules, and any occupancy-related standards that may apply. If a property is part of an HOA or condominium association, ask for the current budget, reserve information, rental policies, pending assessments, and insurance details. These documents can materially affect both monthly cash flow and future marketability.
A property with a lower purchase price is not automatically the stronger investment. HOA dues, flood insurance, deferred maintenance, rental restrictions, and management costs can change the annual return far more than a small difference in the sale price.
Location still matters, but it should be evaluated through measurable factors rather than broad impressions. Consider driving distance to beach access, regional employment centers, medical services, grocery options, recreation, major routes, and public amenities. Look at the property itself as carefully as the map: parking capacity, storage, bedroom count, layout, outdoor areas, condition, and ease of maintenance all influence renter interest and resale demand.
Build a Realistic Annual Cost Estimate
A sound ROI analysis captures more than the mortgage payment. Start with acquisition costs, including down payment, lender fees, title charges, inspections, appraisal, settlement expenses, and any immediate repairs or furnishing needs. Then separate recurring expenses from irregular but expected costs. This produces a more useful operating picture than relying on a single monthly payment.
- Financing: principal, interest, mortgage insurance if applicable, and lender-required reserves.
- Property taxes: verify the current assessment and ask how a sale may affect future tax obligations.
- Insurance: obtain a property-specific quote early, including wind, flood, landlord, liability, or condominium coverage as needed.
- HOA or condominium dues: include regular dues, special assessment history, and services covered by the association.
- Utilities: account for water, sewer, electric, internet, trash, lawn care, pest control, and seasonal service where applicable.
- Maintenance and capital reserves: budget for routine repairs as well as major items such as roofing, HVAC systems, appliances, siding, decks, and exterior drainage.
- Management and leasing: include management fees, advertising, tenant placement, cleaning, turnover, bookkeeping, and payment processing where relevant.
For a simple cash-flow estimate, subtract all annual operating costs and annual debt service from projected annual rental income. The result is pre-tax cash flow. To estimate cash-on-cash return, divide that annual pre-tax cash flow by the total cash invested at purchase, including the down payment and closing costs. Cap rate is another useful comparison tool: divide net operating income, before debt service, by the purchase price. Neither metric is complete by itself, but together they help investors compare opportunities with different financing structures.
Be conservative with the assumptions. Allow for vacancy, slower booking periods, turnover time, repairs, and rent that may be lower than an optimistic online estimate. Rental income can change as competing inventory, interest rates, consumer travel patterns, local rules, and property condition evolve. A property that remains workable under a cautious projection is usually more resilient than one that depends on perfect occupancy and no surprise expenses.
Estimate a monthly mortgage payment
Test Rental Income Against Comparable Properties
Rental projections should come from comparable homes, not from a property’s asking price or a generic regional average. Compare residences with similar location, size, condition, parking, outdoor spaces, furnishing level, amenities, and rental format. A three-bedroom home with updated systems and easy access to regional destinations may command a different rate than a similarly sized home with fewer conveniences or higher monthly association costs.
For annual rentals, review recent leased comparables when available and distinguish between advertised rent and completed lease terms. For seasonal or short-term planning, examine the likely number of rentable weeks, anticipated average nightly or weekly rate, platform fees, cleaning frequency, supply replacement, and management costs. Do not assume every calendar date will produce the same revenue. Shoulder-season demand and vacancy periods should be part of the model from the beginning.
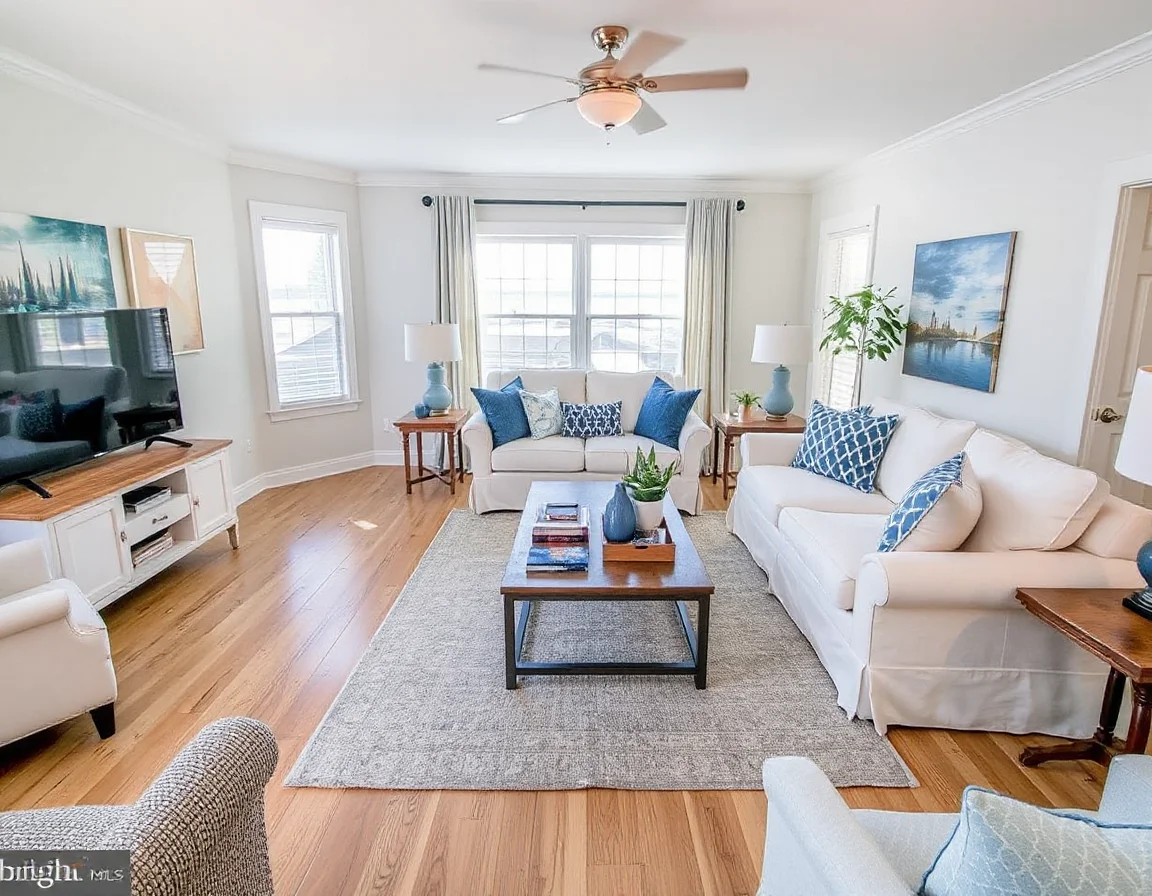
Property condition can protect income. Clean exterior presentation, refreshed paint, dependable mechanical systems, functional storage, and well-planned furnishings can help reduce avoidable maintenance issues and support strong listing presentation. However, upgrades should be selected with the exit strategy in mind. An improvement that makes the home easier to maintain or broadly appealing at resale may be more valuable than a highly customized feature with limited buyer interest.
Keep records from day one. Save invoices, maintenance notes, warranties, rental statements, improvement receipts, association documents, and insurance information. Organized documentation helps track performance over time and can make future due diligence easier for a prospective buyer. Consult qualified tax, legal, insurance, and lending professionals for advice tailored to your ownership structure and goals.
Plan the Resale Before You Buy
Rental income is only one side of total return. Appreciation is never guaranteed, yet resale potential deserves attention because market conditions can change during any ownership period. In Selbyville, properties that are well maintained, appropriately priced for their condition, and easy to understand for a future buyer often have a clearer path to market. Layout, bedroom count, parking, community rules, monthly fees, lot condition, and proximity to regional amenities can all affect the future buyer pool.
Consider how the home will show after years of use. Durable flooring, low-maintenance exterior materials, a practical kitchen, neutral finishes, and updated systems can support both day-to-day ownership and eventual sale preparation. If the home is used as a rental, establish a maintenance schedule rather than waiting for a sale to address deferred items. A last-minute repair list can reduce proceeds, delay listing preparation, or complicate negotiations.
The strongest exit strategy is often simple: buy with enough margin to maintain the property properly, document improvements, and avoid relying on an unusually high future sale price to make the investment work.
Before submitting an offer, run more than one scenario. Model a favorable year, a typical year, and a slower year with higher repairs or lower occupancy. Review how changing interest rates, insurance premiums, HOA costs, or rent levels would affect the plan. This sensitivity check is especially valuable for beach-region investments, where weather exposure, insurance requirements, and seasonal patterns can influence ownership costs.
A thoughtful Selbyville investment analysis balances present cash flow with long-term flexibility. When the numbers account for real costs, rental rules, upkeep, and resale considerations, buyers can make decisions with greater clarity. The best opportunity is not necessarily the property with the biggest projected revenue—it is the one whose performance remains credible after the full cost of ownership is included.