A rental property can look promising on paper until taxes, insurance, vacancy, maintenance, and financing enter the calculation. A practical Sussex County ROI review turns projected rent into a clear monthly cash-flow estimate and helps investors compare properties on the same terms. The goal is not simply to find the highest rent, but to identify a property whose income, costs, condition, and operating plan work together.
Start With the Income the Property Can Realistically Produce
Rental-property analysis begins with income, but the advertised rent is only the first line of the worksheet. In Sussex County, Delaware, the appropriate rental strategy may differ considerably between a year-round lease, a furnished seasonal arrangement, and a vacation rental with changing weekly demand. Before making an offer, identify the use that is permitted by local rules, the community association, the lender, and the insurance provider. Then compare the property with genuinely similar rentals by location, bedroom count, condition, parking, outdoor space, furnishings, and proximity to the coast or other local amenities.
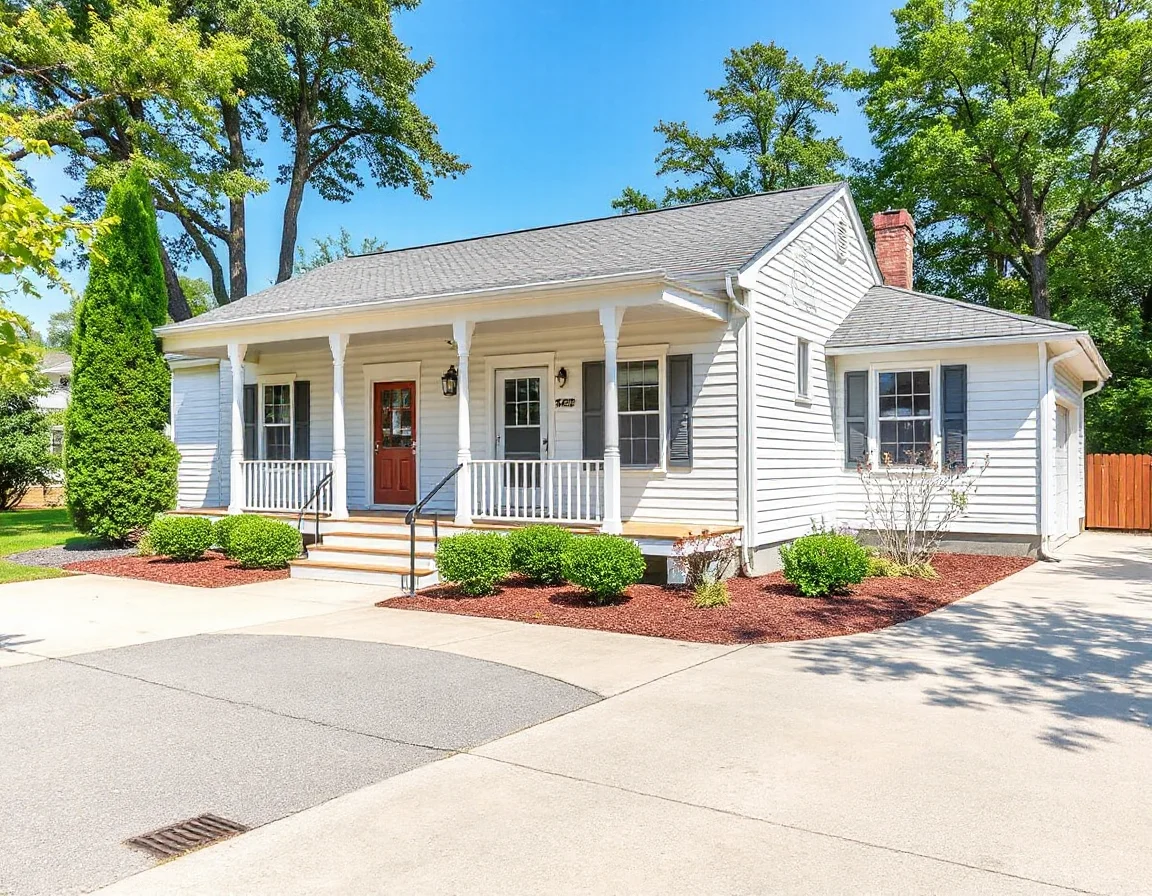
For a long-term rental, use a conservative monthly market-rent estimate rather than the most optimistic online listing. If comparable homes indicate a likely rent of $2,100 per month, the starting point is $25,200 in annual gross potential rent. For a short-term rental, build the estimate month by month: expected nightly rate multiplied by expected occupied nights, less platform fees and any owner-paid services. Coastal demand can be highly seasonal, so a strong summer calendar should not be used to assume the same revenue in every month of the year.
Other income can matter, but it should be supported by evidence. A permitted parking fee, pet fee where allowed, storage fee, or utility reimbursement may add revenue; projected income from an unapproved feature should not. Investors also benefit from reviewing the last 12 months of utility bills, rental history, booking statements when available, and any existing lease. These records make the estimate more durable than a quick calculation based on a single advertised rate.
Use a vacancy allowance even when demand appears strong. Setting aside 5% to 10% of potential rent creates room for turnover, off-season gaps, or time needed for repairs and marketing.
After deducting vacancy and credit loss, the result is effective gross income. In the $25,200 example, a 7% vacancy reserve reduces projected collected rent by $1,764, leaving $23,436 before operating expenses. That figure is far more useful than headline rent when comparing one Sussex County property with another.
Build a Full Operating-Cost Picture
Operating expenses are the costs required to hold, maintain, insure, and rent the property, excluding the mortgage payment. Taxes and insurance should be based on current quotes and public records, not an old owner’s bill alone. Coastal and near-coastal properties may carry insurance considerations that deserve particular attention, including wind, flood, deductible structure, and coverage requirements. A quote obtained during due diligence can prevent a meaningful surprise after settlement.
Common annual expenses include property taxes, homeowners insurance, flood insurance where applicable, homeowners or condominium association dues, utilities paid by the owner, landscaping, pest service, accounting, licensing, cleaning, and property management. A condominium’s monthly dues may cover items such as exterior maintenance, water, trash service, amenities, or master insurance, but the details vary. Read the association documents carefully and account for special assessments or reserve concerns rather than treating dues as the only association-related cost.
Maintenance and capital expenditures deserve separate lines. Maintenance covers recurring repairs such as plumbing service, appliance fixes, paint touchups, and minor exterior work. Capital expenditures are larger, infrequent replacements: roof work, HVAC replacement, windows, flooring, decking, or major appliance upgrades. A property can produce positive cash flow for a year while still carrying an underfunded replacement need. Reserving a percentage of income each month helps the analysis reflect the real life of the building.
For example, an investor might estimate $2,900 for taxes, $2,600 for insurance, $1,800 for association dues, $1,400 for owner-paid utilities, $2,300 for management, $1,700 for maintenance, and $1,500 for capital reserves. Total operating expenses would be $14,200. Subtracting that amount from $23,436 in effective gross income produces an estimated net operating income, or NOI, of $9,236. The exact mix will differ property by property, but the disciplined structure remains the same.
A lower purchase price is not automatically a better investment. Deferred maintenance, high association dues, insurance exposure, or limited rental flexibility can change the return more than the asking price alone.
Measure Cash Flow, Cap Rate, and Return on Cash Invested
Once NOI is established, investors can calculate several useful performance measures. Capitalization rate, or cap rate, is NOI divided by purchase price. If a property purchased for $325,000 produces $9,236 in NOI, the estimated cap rate is about 2.8%. Cap rate is useful for comparing properties without financing, but it does not reveal what remains in an owner’s bank account each month.
Cash flow answers that next question. Start with NOI and subtract annual debt service: principal and interest payments on the mortgage. Also include any recurring financing-related costs not already included in operating expenses. If annual debt service is $16,200, the example property would show negative annual cash flow of $6,964 before income taxes. That does not necessarily make the property unsuitable, but it means the investment depends on other objectives, such as future appreciation, personal use where permitted, principal paydown, or a different financing structure. It should be a conscious decision rather than an overlooked result.
Cash-on-cash return compares pre-tax annual cash flow with the actual cash invested. Include the down payment, closing costs, initial repairs, furnishings, and startup reserves. An investor who contributes $100,000 in total cash and receives $5,000 of annual pre-tax cash flow has a 5% cash-on-cash return. This measure is especially helpful when comparing a higher-priced property with stronger income against a lower-priced property needing extensive work.
- Gross potential rent: income if fully occupied at projected rates.
- Effective gross income: projected rent after vacancy, collection loss, and supported other income.
- NOI: effective gross income minus operating expenses, before mortgage payments.
- Cash flow: NOI minus debt service and other financing obligations.
- Cash-on-cash return: annual pre-tax cash flow divided by total cash invested.
Run a sensitivity test before relying on any single result. What happens if rent is 10% lower, if insurance increases, if one major system fails, or if occupancy falls during a slower season? A rental plan that still works under a modest downside scenario is generally more resilient than one that depends on perfect pricing and uninterrupted bookings.
Match the Property’s Condition and Rules to Your Operating Plan
Numbers only work when the property can support the intended rental model. During due diligence, review zoning, rental-license requirements, association rules, lease restrictions, parking rules, pet policies where applicable, occupancy rules, and any limitations on short-term rentals. For condominiums and planned communities, request the current governing documents, budget, meeting minutes, insurance information, and resale package early. These materials can reveal pending projects, rental caps, or operational details that affect both income and expenses.
Condition also influences more than repair costs. Durable flooring, easy-to-maintain exterior materials, efficient systems, functional storage, and a well-planned kitchen can reduce turnover work and simplify ongoing maintenance. In beach-area locations, inspect exterior finishes, decks, railings, HVAC components, drainage, windows, and moisture-prone areas with particular care. A professional inspection is not a substitute for financial analysis, but it gives the financial analysis the facts it needs.
Make the Decision With a Clear Reserve Plan
A sound Sussex County rental-property decision combines conservative income, complete expenses, financing costs, property condition, and the rules that govern its use. Keep a reserve fund for unexpected repairs, deductible payments, turnover periods, and seasonal fluctuations rather than directing every available dollar toward the down payment. Review the spreadsheet with current lender terms and current insurance estimates shortly before making a final decision.
The best ROI analysis is not the one with the prettiest projected number. It is the one that makes assumptions visible, tests them under realistic conditions, and gives the owner a workable plan for the months when revenue is lower or expenses are higher. With that discipline, investors can evaluate Sussex County opportunities with greater clarity and select properties that align with their own financial goals and risk tolerance.